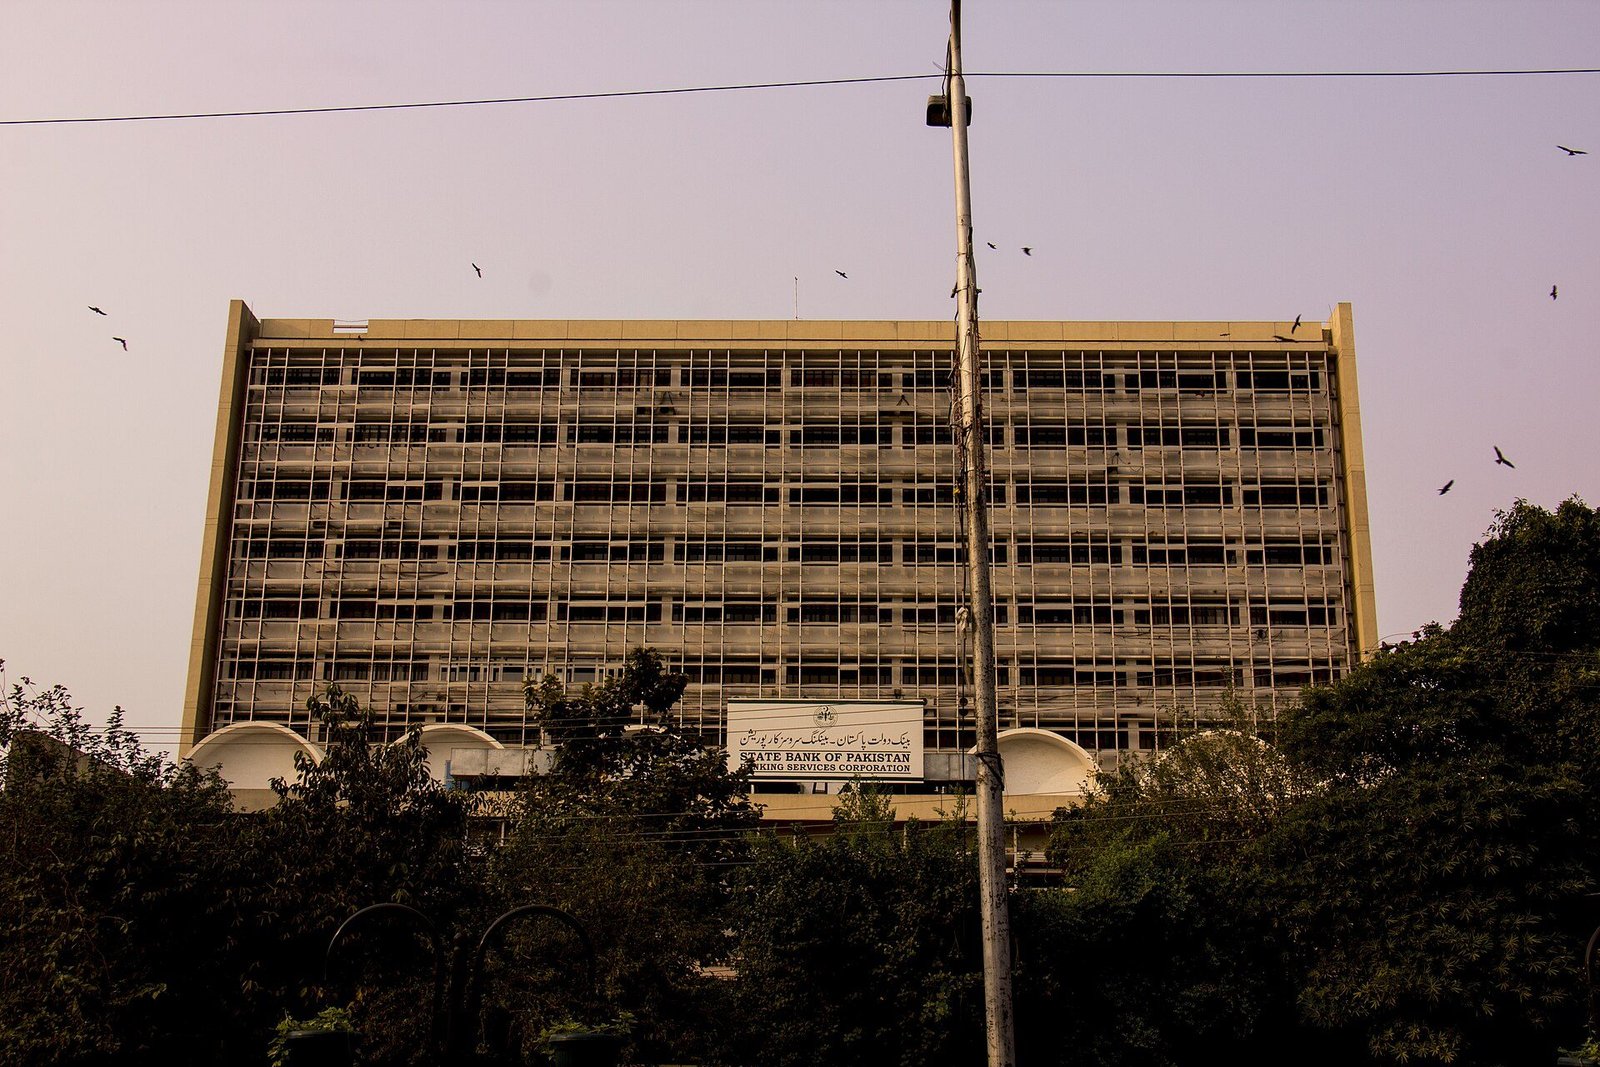
Tag: builders financing

  • اسٹیٹ بینک نے بلڈرز کی فنانسنگ کی اجازت دے دی

    اسٹیٹ بینک نے بلڈرز کی فنانسنگ کی اجازت دے دی

    اسٹیٹ بینک آف پاکستان (ایس بی پی) نے بلڈرز اور ڈویلپرز کی فنانسنگ کے لیے نظرثانی شدہ ہدایات جاری کر دی ہیں، جس کے تحت بینک اور ترقیاتی مالیاتی ادارے (ڈی ایف آئیز) ہاؤسنگ منصوبوں کو قرض دے سکیں گے۔ اس اقدام کا مقصد ملک بھر میں رہن کے قابل مکانات کی فراہمی بڑھانا ہے۔

    مرکزی بینک نے یہ نظرثانی شدہ فریم ورک بدھ 18 نومبر 2026 کو جاری کردہ ایک سرکلر کے ذریعے نافذ کیا، جس سے اپریل 2014 میں جاری کردہ ہدایات کی جگہ لے لی گئی ہے۔ نئے قواعد تمام بینکوں اور ڈی ایف آئیز پر لاگو ہوں گے اور ان میں رئیل اسٹیٹ انویسٹمنٹ ٹرسٹس (ریٹس)، سرکاری اور نجی بلڈرز و ڈویلپرز کے ساتھ ساتھ اہل سرکاری ہاؤسنگ اتھارٹیز اور پبلک سیکٹر ڈویلپمنٹ ادارے بھی شامل ہیں۔

    مرکزی بینک کے مطابق قابلِ اعتماد بلڈرز اور ڈویلپرز کو فنانسنگ کی فراہمی ہاؤسنگ کی سپلائی بڑھانے میں ایک اہم خلا ہے، اور نظرثانی شدہ ہدایات کا مقصد بینکوں اور ڈی ایف آئیز کو اس شعبے کو قرض دینے کی ترغیب دینا ہے، جبکہ رسک مینجمنٹ کے معیارات بھی برقرار رکھے جائیں گے۔

    فنانسنگ کون حاصل کر سکتا ہے

    نظرثانی شدہ فریم ورک کے تحت ریٹس اور سرکاری و نجی بلڈرز و ڈویلپرز فنانسنگ کے اہل ہوں گے۔ سرکاری شعبے کے اداروں میں فیڈرل گورنمنٹ ایمپلائز ہاؤسنگ اتھارٹی (ایف جی ای ایچ اے)، پی ایچ اے فاؤنڈیشن، صوبائی و علاقائی ہاؤسنگ اتھارٹیز اور صوبائی حکومت کے زیرِ کنٹرول ٹاؤن پلاننگ ادارے شامل ہیں۔

    قرض لینے والے کے پاس متعلقہ بلڈنگ کنٹرول اتھارٹی سے جاری کردہ درست بلڈر یا ڈویلپر لائسنس ہونا ضروری ہے، یا مجاز سرکاری ادارے سے منظور شدہ معاہدہ ہونا چاہیے۔ نجی بلڈرز کو منصوبے مکمل کرنے کا اچھا ریکارڈ بھی پیش کرنا ہوگا۔ منصوبے کی زمین کا ٹائٹل صاف ہونا چاہیے، اس پر کوئی بوجھ یا لین نہ ہو، اور زمین کی قیمت کو بلڈر کی ایکویٹی تصور کیا جائے گا۔

    دستاویزات اور منصوبے کی جانچ

    بینک اور ڈی ایف آئیز درخواست گزار سے رجسٹریشن دستاویزات، تین سال کی مالیاتی گوشوارے، انکم ٹیکس ریٹرنز، ٹیکس اسسمنٹ ریکارڈ اور خفیہ بینکنگ رپورٹس طلب کر سکتے ہیں۔ 500 ملین روپے سے زائد کی فنانسنگ کے لیے تازہ ترین آڈٹ شدہ مالیاتی گوشوارے ایس بی پی کے پینل پر موجود آڈٹ فرم سے تصدیق شدہ ہونے چاہئیں۔

    منصوبے کی دستاویزات میں صاف ٹائٹل دستاویزات، منظور شدہ بلڈنگ پلان، نان انکمبرنس سرٹیفکیٹ، تعمیر اور فروخت کی منظوریاں، جائیداد رہن رکھنے کی اجازت اور متعلقہ ماحولیاتی کلیئرنسز شامل ہونی چاہئیں۔ ہر منصوبے میں فنانسنگ کی واپسی کے لیے کافی کیش فلو پیدا کرنے کی صلاحیت ہونی چاہیے، اور اس کی تکنیکی فزیبلٹی رپورٹ کا آزادانہ جائزہ پاکستان انجینئرنگ کونسل جیسے ادارے سے رجسٹرڈ معروف انجینئرنگ فرم سے کروانا ہوگا۔

    ویلیوایشن اور نگرانی

    ہدایات میں فنانسنگ کی رقم کے حساب سے ویلیوایشن کی شرائط مقرر کی گئی ہیں۔ 50 ملین روپے تک کے قرضوں کے لیے بینک یا ڈی ایف آئی کی ڈیسک ٹاپ ویلیوایشن کافی ہوگی، 50 ملین سے 500 ملین روپے تک کی فنانسنگ کے لیے کم از کم ایک منظور شدہ ویلیوئر کی ویلیوایشن ضروری ہوگی، جبکہ 500 ملین روپے سے زائد رقم کے لیے کم از کم دو ویلیوئرز کی ویلیوایشن لازمی ہوگی۔

    بینکوں اور ڈی ایف آئیز کو تعمیراتی پیش رفت کی نگرانی کرنی ہوگی، ہر چھ ماہ میں کم از کم ایک بار منصوبوں کا معائنہ کرنا ہوگا اور منصوبے کے کھاتوں اور مالی شرائط کا جائزہ لینا ہوگا۔ فنڈز کے غلط استعمال کو روکنے کے لیے مشترکہ طور پر چلایا جانے والا ایسکرو اکاؤنٹ لازمی ہوگا، اور ڈویلپرز کو تعمیراتی انشورنس یا اس کے مساوی تکافل کوریج حاصل کرنا ہوگی۔ مرکزی بینک نے بینکوں اور ڈی ایف آئیز کو بلڈرز اور ڈویلپرز کے لیے فنانسنگ پورٹ فولیو بڑھانے کے لیے خصوصی یونٹس قائم کرنے کی بھی ترغیب دی ہے۔

    یہ نظرثانی شدہ فریم ورک یکم اپریل 2014 کے آئی ایچ اینڈ ایس ایم ای ایف ڈی سرکلر نمبر 02 کے تحت جاری کردہ ہدایات کی جگہ لے گا۔ عارف حبیب لمیٹڈ کے مرتب کردہ اعداد و شمار کے مطابق اکتوبر 2026 میں پاکستان میں ہاؤسنگ فنانس 409 ارب روپے تک پہنچ گیا تھا۔

  • SBP Allows Banks to Finance Builders, Developers

    SBP Allows Banks to Finance Builders, Developers

    The State Bank of Pakistan (SBP) has issued revised guidelines allowing banks and development finance institutions (DFIs) to finance builders and developers, in a move aimed at increasing the supply of mortgageable housing units across the country.

    The central bank issued the revised framework through a circular on Wednesday, November 18, 2026, updating the guidelines originally introduced in April 2014. The new rules apply to all banks and DFIs and cover Real Estate Investment Trusts (REITs), public and private builders and developers, as well as eligible government housing authorities and public-sector development entities.

    According to the central bank, financing for creditworthy builders and developers remains a critical gap in expanding the supply of housing, and the revised guidelines are designed to encourage banks and DFIs to lend to the sector while keeping risk management standards in place.

    Who can get financing

    Under the revised framework, REITs and public and private builders and developers are eligible for financing. Public-sector entities covered by the rules include the Federal Government Employees Housing Authority (FGEHA), the PHA Foundation, provincial and territorial housing authorities, and town-planning bodies owned or controlled by a provincial government.

    Borrowers must hold a valid builder or developer licence from the relevant building control authority, where applicable, or an approved contract from the competent public-sector authority. Private builders must also show a good track record of completing projects, supported by a list of recently completed developments. The project land must have a clear title, free of encumbrance, charges and liens, and its value will be treated as the builder’s equity in the project.

    Documents and project checks

    Banks and DFIs may ask for registration documents, three years of financial statements, income tax returns, tax assessment records and confidential banking reports. For financing above Rs500 million, the latest audited financial statements must be certified by an audit firm on the SBP panel.

    Project documentation must include clear title documents, an approved building plan, a non-encumbrance certificate, construction and sale approvals, permission to mortgage, and relevant environmental clearances. Each project must generate enough cash flow to repay its financing, and its technical feasibility report must be independently reviewed by a reputed engineering firm registered with a body such as the Pakistan Engineering Council.

    Valuation and monitoring

    The guidelines set valuation requirements based on the size of the financing. Loans of up to Rs50 million may rely on desktop valuations by the bank or DFI, financing above Rs50 million and up to Rs500 million requires at least one valuation by an approved valuer, and amounts above Rs500 million require valuations by at least two valuers.

    Banks and DFIs must monitor construction, inspect projects at least once every six months, and review project accounts and financial covenants. A jointly operated escrow account will be mandatory to prevent the diversion of funds, and developers must obtain construction insurance or equivalent Takaful coverage. The central bank has also encouraged banks and DFIs to set up specialised units to expand their financing portfolios for builders and developers.

    The revised framework replaces the guidelines issued under IH&SMEFD Circular No. 02 dated April 1, 2014. According to data compiled by Arif Habib Limited, housing finance in Pakistan stood at Rs409 billion in October 2026.